

Expanding into a new practice area is a big opportunity, but it comes with strict legal and ethical rules. Missing even small details can lead to disciplinary actions, fines, or malpractice claims. Here’s what you need to know upfront:
- Compliance is critical: In 2024, 18,000 disciplinary cases were filed in California alone. Malpractice claims affect 4–5% of attorneys annually, costing an average of $154,000 per claim.
- Costs add up: HIPAA violations can cost $1.5M per instance, and a data breach in 2024 averaged $4.88M.
- Preparation is key: From licensing and trust accounting to data protection, every step matters. Jurisdiction-specific rules like ABA Model Rule 5.5 and trust accounting requirements (e.g., IOLTA) must be followed.
A clear checklist helps ensure compliance with licensing, client funds management, and data security. Use tools like legal software for trust accounting and conflict checks, and update firm policies to reflect new practice needs. Regular audits and staff training complete the process, ensuring your firm avoids costly mistakes while building trust with clients.
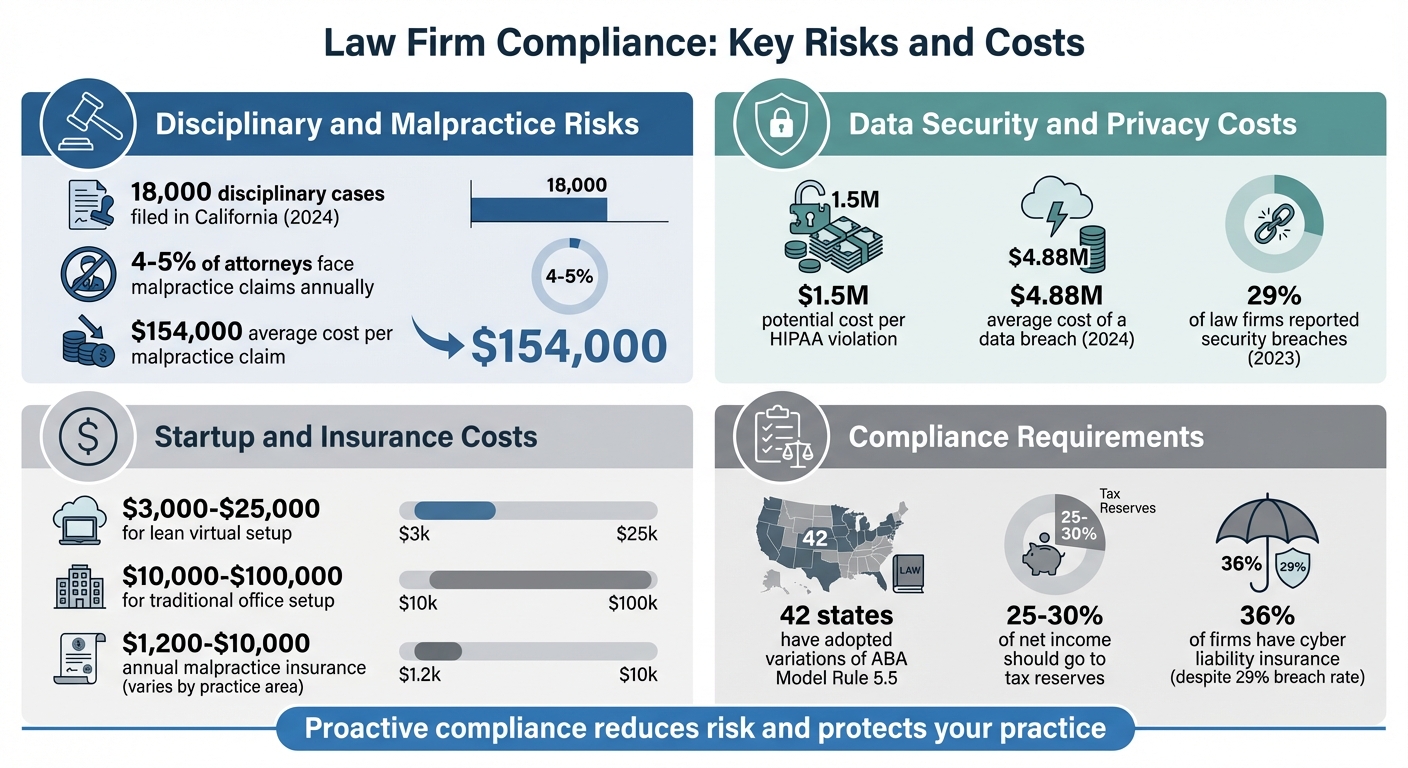
Law Firm Compliance Risks and Costs by Category
Assess Practice Area Fit and Firm Readiness
Before diving into a new practice area, it’s crucial to evaluate whether your firm has the right expertise, resources, and market positioning. Skipping this step can lead to compliance issues, financial strain, or damage to your reputation.
Evaluate Alignment with Firm Expertise
Start by ensuring the new practice area aligns with your firm’s existing skills and client base. Ideally, your firm should have 2–3 years of direct experience in the proposed area, with attorneys who can independently manage cases from start to finish. Without this experience, you may face ethical risks and malpractice exposure.
Your next step is to define your firm’s Unique Value Proposition (UVP). Identify your target clients, the specific problem you aim to solve, and what sets you apart from competitors. This clarity ensures your new direction aligns with your firm’s mission and goals. Additionally, assess the local market – both the economic environment and competition – to confirm demand. Having 3–5 potential clients ready to hire can validate the need for your services.
“Success isn’t about being the best lawyer – it’s about being the best at running a law business.” – Alison Elliot, Author, LeanLaw
To build credibility and connections, consider joining local bar association sections relevant to the new practice area. This can help you find mentors and develop valuable word-of-mouth referrals.
Once you’ve evaluated your expertise and market fit, it’s time to assess your firm’s operational readiness.
Conduct an Internal Resource Audit
An internal audit will help determine if your firm can handle the new practice area without stretching resources too thin. Focus on three key areas: staffing, technology, and financial preparedness.
- Staffing: Ensure your team has the experience to handle cases independently. If hiring new staff, account for costs like paralegal salaries, which range from $2,500 to $4,000 per month.
- Technology: Review your software setup. Essential tools include practice management software ($69–$300 per month), document management systems with version control, and legal-specific accounting software like QuickBooks Online ($30–$70 per month). Firms using modern practice management tools report higher satisfaction with client relationships. Make sure your team has the necessary hardware, like laptops and scanners, within budget.
- Financial Reserves: Confirm you have enough savings or credit to cover startup costs and at least six months of overhead expenses. Starting a law firm in 2024–2025 costs anywhere from $3,000–$25,000 for a lean virtual setup to $10,000–$100,000 for a traditional office. Allocate 25–30% of your net income to a separate tax reserve account.
To stay organized, draft a comprehensive business plan. Include an executive summary, cost analysis, billing projections, and a break-even analysis. Implement a 90-Day Roadmap to phase your efforts: focus on legal structure and banking in the first month, technology and operations in the second, and marketing in the third.
Once your internal capabilities are squared away, turn your attention to jurisdiction-specific requirements.
Understand Jurisdiction-Specific Requirements
Every jurisdiction has its own set of rules for practice areas, licensing, and business operations. Overlooking these can lead to unauthorized practice of law (UPL) violations or disciplinary actions.
- Licensing and UPL: ABA Model Rule 5.5 restricts practicing in jurisdictions where you’re not admitted. However, 42 states have adopted variations of this rule, each with its own “safe harbor” provisions. For instance, Missouri requires local admission, while Oregon allows remote work under certain conditions.
- Choice of Law Rules: Under Model Rule 8.5, determine which state’s ethics rules apply to your practice. For tribunal-related conduct, the jurisdiction’s rules apply; for other conduct, the rules of the jurisdiction with the “predominant effect” are used.
“A lawyer must comply with the ethics rules of the jurisdiction in which the lawyer intends to provide advice and in which the lawyer is located when providing the advice.” – American Bar Association
- Entity Structure and Registration: States vary on permitted business entities like LLPs, PLLCs, or Professional Corporations. Some, like New Jersey, require out-of-state lawyers to register with the supreme court and appoint a local agent for service of process, even for occasional practice.
- Trust Accounting (IOLTA): Many jurisdictions mandate participation in trust account programs. For example, the District of Columbia requires participation in the IOLTA program for lawyers handling eligible funds, effective August 1, 2010.
To meet compliance requirements, consider associating with local counsel under Model Rule 5.5(c). If litigation is involved, research pro hac vice rules, as they vary widely between jurisdictions.
sbb-itb-95f4849
Research and Document Regulatory and Ethical Requirements
Building a solid compliance framework for your new practice area starts with documenting regulatory and ethical requirements. Missing even a single detail could leave your firm vulnerable to disciplinary action or malpractice claims.
Identify Applicable Laws and Regulations
Start by mapping out the federal, state, and local laws relevant to your practice. This includes professional conduct rules, business entity laws, trust accounting requirements, and advertising regulations.
Most jurisdictions base their ethics rules on the ABA Model Rules of Professional Conduct, but each state tailors these rules to address local nuances. For instance, Vermont has its own Rule 1.15A, while states like Texas, Virginia, and Washington have specific versions of Rule 5.8, which governs law firms and associations. Ensuring compliance requires understanding your jurisdiction’s exact rules.
In addition to ethics rules, handle business formation and tax requirements by registering your entity (e.g., LLP, PLLC, or Professional Corporation) with your state’s Secretary of State and obtaining an Employer Identification Number (EIN) from the IRS.
If your practice involves client funds, familiarize yourself with your state’s trust accounting requirements. For example, Texas mandates IOLTA accounts to be opened at approved banks and requires filing a “New Account/Notice” form with the Texas Access to Justice Foundation. Researching these requirements early is critical.
Review advertising regulations specific to your jurisdiction. In Texas, attorneys must submit advertisements and solicitation communications to the Advertising Review Department under Part VII of the Texas Disciplinary Rules of Professional Conduct.
| Regulatory Category | Primary Source/Authority | Documentation Method |
|---|---|---|
| Ethical Standards | State-specific Rules of Professional Conduct (based on ABA Model Rules) | Internal compliance checklists; Jurisdictional comparison charts |
| Business Structure | Secretary of State; IRS | Entity formation filings; EIN confirmation |
| Client Funds | State IOLTA Rules (e.g., D.C. Rule 1.15) | IOLTA Notice forms; Trust accounting software logs |
| Communications | State Bar Advertising Review Departments | Submission of ads for review; Retainer agreement disclaimers |
| Client Relations | State Ethics Opinions (e.g., TX Opinion 611) | Engagement letters; Closing letters |
Once you’ve mapped these requirements, align your findings with ABA and state-specific guidelines.
Consult ABA Model Rules and State Bar Guidelines
After identifying relevant laws, compare them to the ABA Model Rules to pinpoint any local modifications. The ABA Model Rules of Professional Conduct form the foundation for ethics rules in most states, but individual jurisdictions often adjust these rules to address specific needs or industries.
For instance, Washington State’s RPC 1.2 includes a unique Comment, which permits lawyers to assist clients in conduct they believe aligns with state law, even if it conflicts with federal law. This adjustment created a safe harbor for practitioners in certain areas.
“Washington (like most states) has adopted the ABA’s Model Rules of Professional Conduct. But adopting the rules is not simply a matter of copying and pasting.” – University of Washington Law Library
To identify such variations, conduct a side-by-side comparison using ABA jurisdictional charts. These resources detail how states modify rules like conflicts of interest (Rule 1.7) or safekeeping property (Rule 1.15).
Pay close attention to Rule 1.1 (Competence), which includes comments on technological competence that vary by jurisdiction. This is particularly important for practice areas that rely on technology or data management.
In addition to the Model Rules, consult ethics opinions from both the ABA and state bar associations to understand how rules are applied in practice. For example, Texas Ethics Opinion 611 clarifies that advance payments for future services are fully refundable, even if labeled “nonrefundable” in agreements.
“Any time you receive money from a client as an advance payment for legal services you will perform in the future, that money is fully refundable, regardless of whether the retainer agreement says it is nonrefundable.” – Texas Bar Practice
The Annotated Model Rules of Professional Conduct is another valuable resource, offering detailed legal research and case law summaries for each rule.
Use Compliance Resources and Tools
Manually tracking regulatory requirements can be overwhelming. Simplify the process with specialized tools and resources.
The ABA/Bloomberg Law Lawyers’ Manual on Professional Conduct is a subscription-based resource offering over 130 chapters of analysis, full texts of ABA ethics opinions, and summaries from more than 60 jurisdictions. A free trial is available via Bloomberg Law.
“The ABA/Bloomberg Law Lawyers’ Manual on Professional Conduct is the complete research resource in the field of professional responsibility law and the most authoritative source for news and guidance on virtually every aspect of attorney conduct and legal ethics.” – American Bar Association
For state-specific help, check if your state bar provides a Practice Management Advisory Service (PMAS). The D.C. Bar, for instance, offers a free Management Resource Line, quizzes, and “Ask the Ethics Experts” services.
Invest in legal practice management software to streamline compliance tracking. Look for tools with features like conflict checking, case management, and trust accounting (IOLTA) capabilities. Some state bars even provide free or discounted software to their members. For example, Smokeball offers its trust accounting and billing software at no cost to members of the D.C. Bar and the State Bar of Texas.
Before expanding into a new jurisdiction, use ABA comparison charts to identify local deviations from the Model Rules. These charts can help you uncover unique requirements, such as Texas Rule 13.04, which allows lawyers to pre-designate a custodian-attorney to manage their practice if they’re unable to do so.
Finally, establish a written file-closing procedure. This should include returning client property and scheduling files for periodic review to meet ethical standards. For example, lawyers in the District of Columbia must retain client files for at least five years after a case closes.
Once you’ve documented these requirements and set up monitoring systems, you’re ready to update your firm’s policies to reflect your new practice area.
Update Firm Policies and Procedures
Revising firm policies to incorporate regulatory requirements is key to safeguarding both your practice and your clients. Existing procedures may not fully address the specific compliance needs of a new practice area, so updates are necessary.
Revise Engagement Letters and Fee Agreements
Once regulatory requirements are clear, update client engagement documents to reflect these changes. Engagement letters should address compliance standards and be tailored to the specific needs of the new practice area.
Clearly identify the client – whether it’s an individual, an estate, or a corporate entity. This helps avoid potential conflicts of interest down the road.
Define the scope of representation in exact terms. If you’re offering limited scope services, specify what is included and excluded. For example, list exclusions such as appeals, insurance investigations, or post-decree matters. New York’s Rule 1.2 allows for such limitations as long as they’re reasonable and the client agrees.
“A lawyer may limit the scope of the representation if the limitation is reasonable under the circumstances, the client gives informed consent and where necessary notice is provided to the tribunal and/or opposing counsel.” – Rule 1.2, New York Rules of Professional Conduct
Fee structures must comply with jurisdictional standards. For flat fees, outline specific milestones or benchmarks that determine when portions of the fee are earned. Contingent fee agreements should state the percentage, clarify how costs are deducted, and explain the client’s liability if there’s no recovery.
Distinguish between engagement retainers (earned upon receipt) and advance payments or subscription fees (held in trust until earned). This distinction is critical because advance payments remain the client’s property until you’ve performed work.
| Fee Type | Compliance Requirement | Handling of Funds |
|---|---|---|
| Hourly | State staff rates | Billed from trust retainer |
| Flat Fee | List milestones; early termination terms | Held in trust; withdrawn as milestones met |
| Contingent | Written agreements; cost deduction details | Paid from recovery; retain copy for 7 years |
| Subscription | Must be reasonable; preclusion of other work | Earned after service is performed |
| Engagement Retainer | For availability only; no future services | Earned upon receipt; deposited in operating account |
Include technology and AI disclaimers to address modern practice realities. Disclose the use of cloud storage and any artificial intelligence tools involved in handling the matter.
For file management, outline policies for maintaining digital and paper records, timelines for file destruction, and the client’s right to retrieve original documents. Texas attorneys, for instance, can include a “designated custodian” clause to inform clients who will manage their files if the attorney becomes unavailable.
Use straightforward language throughout these documents. Legal jargon can confuse clients and may lead to disputes. For existing clients, consider adding a fee addendum instead of drafting entirely new agreements to reflect changes in scope or rates.
“The single most important document that defines the attorney-client relationship is the retainer agreement or engagement letter.” – Allison C. Shields, Author, New York State Bar Association
Establish Practice-Specific File Management Protocols
New practice areas often require different documentation, deadlines, and retention policies, so having a standardized approach is critical.
Develop a file opening checklist that includes conflict checks, client identity verification, entering key dates into calendars, adding the matter to a Master File List, and sending retainer letters. This ensures ethical safeguards are in place from the start.
“It is surprising to discover how many steps are performed to open a file. Writing out your file opening procedure and creating a checklist will help to maintain consistency.” – Law Society of Alberta
Assign each client matter a unique identifier or file number for easy tracking across accounting and case management systems, especially when handling multiple matters for the same client.
Create naming conventions and folder structures tailored to the practice area. For instance, set up standard folders for pleadings, discovery, correspondence, and exhibits. This consistency ensures that any attorney in the firm can quickly locate documents.
Automate deadline tracking by immediately entering key dates – such as statutes of limitation and filing deadlines – into a centralized calendar when a file is opened. Missing a deadline in an unfamiliar practice area could lead to malpractice claims.
Ensure security measures are in place for both physical and digital files. Lock physical files at the end of each day, and secure electronic files against unauthorized access.
Establish a file closing process that includes returning original documents to the client, removing attorney work product, and setting a destruction date. Send a closing letter to clients explaining your retention policy and giving them the option to retrieve their files.
“A consistent process ensures ethical compliance, efficient administration, and clear client communication from the very start.” – Louisiana Legal Ethics
Maintain a Master Client List that includes client contact information, matter descriptions, file locations, and details of funds held in IOLTA accounts. This list is invaluable for quickly locating files or ensuring continuity if a custodian attorney needs to step in.
Ensure Trust Accounting and Billing Compliance
Launching a new practice area requires strict adherence to trust accounting rules and billing practices. Separate accounts and specialized software can help ensure compliance.
Open distinct accounts for firm operations, IOLTA funds, and non-IOLTA trust funds. Most jurisdictions, including D.C., mandate strict segregation of assets under Rule 1.15.
“D.C. Rule of Professional Conduct 1.15 was amended to make participation in the D.C. IOLTA program mandatory for D.C. lawyers who receive IOLTA–eligible funds.” – D.C. Bar
Consult a CPA or bookkeeper to set up a Chart of Accounts and establish accounting procedures specific to the financial needs of the new practice area.
Within your case management system, set up billing codes tailored to the new practice area. This allows for detailed reporting and helps track both profitability and compliance.
Deposit retainers immediately into a trust account upon receipt, as required by Rule 1.15. Only transfer earned fees to your operating account after billing for completed work. Never mix client funds with firm funds.
Regularly monitor retainer balances and notify clients when their balance runs low to ensure uninterrupted service.
For matters involving co-counsel, disclose any fee-sharing arrangements in writing to the client, as required by ethics rules.
Use specialized software for time tracking, billing, and trust accounting. Tools like The Legal Assistant can automate these processes while ensuring compliance with the separation of operating and trust accounts.
Implement Staff Training and Onboarding
Once your firm’s policies are updated, the next step is ensuring your team has the tools and knowledge to put those changes into action. Without proper training, the risk of compliance issues and ethical missteps increases significantly. Your staff needs to fully grasp trust accounting rules, file management protocols, and any specific regulatory requirements tied to the new practice area. This step bridges updated policies with day-to-day operations, ensuring compliance becomes second nature for every team member.
Develop Practice-Specific Training Programs
Your training should focus on two critical areas: staying compliant with legal standards and improving operational efficiency. Key topics to prioritize include:
- Trust accounting and billing: Since August 1, 2010, D.C. lawyers handling IOLTA-eligible funds must participate in the D.C. IOLTA program. Staff must know how to distinguish between trust and operating accounts and understand that advance payments for future services are fully refundable until earned.
- Fee agreement standards: Cover flat fees, guidelines for retainers, and clear refund policies to ensure consistency and transparency.
- File management: Train staff on the importance of returning original client documents, maintaining both digital and paper records, and adhering to file destruction schedules.
- Technology integration: Teach staff how to use legal practice management software, conflicts-check systems, and secure document-sharing tools effectively.
- Risk management: Include malpractice insurance basics, cyber liability protections, and the process for designating a custodian attorney for sole practitioners.
- Jurisdiction-specific rules: Ensure staff understand the requirements for firm naming, advertising reviews, and the ethical use of artificial intelligence in legal work.
Standardize Onboarding Procedures
A well-structured onboarding process can make all the difference. Employees who experience effective onboarding report 2.6× greater workplace satisfaction and reach full productivity faster. To streamline this, break onboarding into three phases: Preboarding (handling paperwork and setting up tech), Orientation (spanning the first week), and a tailored 30/60/90-day plan for deeper role integration.
Role-specific training is essential. For example, associates may focus on matter intake and legal templates, while support staff concentrate on filing, e-filing, and calendaring. Use practice-specific templates for engagement letters and retainer agreements to ensure consistency in fee benchmarks, privacy policies, and file destruction practices.
Pair new hires with mentors or onboarding buddies to help them navigate the firm’s unique culture and technical requirements. Centralize resources with a digital welcome packet and a repository of onboarding checklists, training modules, and compliance guidelines. Before their first day, ensure all hardware, software logins, and tools are ready to avoid unnecessary delays.
Assign Roles and Set Compliance Deadlines
After onboarding, it’s crucial to assign clear roles and responsibilities to maintain compliance. When everyone knows their part, tasks are less likely to be overlooked.
Firm leaders and partners should set the tone by defining onboarding goals and ensuring compliance with legal and ethical standards. Larger firms may appoint a Chief Compliance Officer (CCO) to oversee these efforts. Managers and practice leaders should conduct regular check-ins, such as 30/60/90-day reviews, to monitor progress and provide feedback on training milestones.
HR and administrative teams play a key role by tracking task completion, managing documentation, and using technology to automate reminders for training deadlines. Mentors provide day-to-day support, helping new hires adapt to firm-specific norms, while local administrators tailor training to meet the needs of specific practice areas.
To prevent inefficiencies, create a repeatable workflow that assigns ownership of tasks to specific team members and timestamps key steps. This not only ensures nothing gets missed but also creates an audit-ready record of completed training. Tools like Learning Management Systems (LMS) or legal practice management software can centralize training materials and automate reminders for compliance deadlines.
“Onboarding becomes a risk reducer and a productivity accelerator – not a paperwork scramble.” – Select Advisors Institute
Finally, schedule regular one-on-one meetings between new hires and their managers to address concerns, provide feedback, and ensure a smooth transition.
Integrate Technology and Monitor Compliance
Once your staff is trained, the next step is integrating reliable technology to maintain compliance. The right tools can shift your approach from reactive to proactive, catching potential issues before they escalate. These tools automate routine checks and create audit trails, reinforcing your firm’s dedication to meeting regulatory requirements. Technology becomes the backbone of your compliance strategy.
Use Legal Practice Management Software
Legal practice management software simplifies compliance by centralizing tasks that might otherwise be overlooked. These platforms often include features like trust accounting with three-way reconciliations, automated conflict checks, and advanced security protocols (e.g., end-to-end encryption, two-factor authentication, SOC 2, HIPAA standards). These measures help safeguard your firm from data breaches, which can be costly. For example, automated CLE tracking ensures your team meets jurisdiction-specific requirements, avoiding fines of $75 to $400 – or even license suspension. Document automation also guarantees that required disclosures are consistently included.
“Effective risk and compliance management requires efficient oversight of information and financial resources, which can be a daunting task without the right tools and strategies in place.” – Christopher Lafferty, General Manager, CARET Legal
Avoid general accounting software for managing trust accounts. Legal-specific platforms like The Legal Assistant are tailored to meet IOLTA requirements and provide the detailed reporting necessary for quarterly audits. Additionally, implement role-based access controls to limit sensitive data access to authorized personnel, reducing the risk of internal breaches. These tools not only streamline compliance but also set the stage for regular audits to ensure your firm stays on track.
Schedule Routine Compliance Audits
Regular audits are essential for maintaining compliance. Internal audits help confirm that your firm adheres to its policies, and scheduling these reviews quarterly can keep you ahead of potential issues. Assign a compliance officer or team to manage the process. Legal practice management software can assist by generating automated reports on trust accounting, billing transparency, and client file statuses – making it easier to identify discrepancies early.
In addition to scheduled reviews, spot audits on trust accounts and KYC records can uncover problems before they escalate. Document all findings in a centralized compliance manual and assign specific follow-up tasks to team members. Regularly verify that technical safeguards like encryption, two-factor authentication, and secure portals are functioning as intended. With 29% of law firms reporting security breaches in 2023, these checks are critical. External audits can also provide an unbiased assessment of your firm’s vulnerabilities. For instance, UK regulators plan to increase Anti-Money Laundering (AML) audits from 200 to 500 by 2025, yet only 22% of law firms currently meet full AML compliance.
Use Automation for Compliance Monitoring
Tracking compliance manually is time-intensive and prone to errors. Automated systems can take over repetitive tasks, such as initiating conflict-of-interest checks when onboarding new clients. Studies show that AI-powered legal intake solutions can reduce compliance violations by 73%.
| Method | Advantages | Disadvantages | Implementation Steps |
|---|---|---|---|
| Manual Tracking | Low software cost; customizable for niche needs. | High error risk; time-consuming; hard to scale. | 1. Use spreadsheets for CLE and trust accounts. 2. Assign staff to update weekly. 3. Manually review for conflicts. |
| Automated Monitoring | Real-time risk alerts; reduces violations by 73%; centralizes data. | Requires setup time and subscription costs. | 1. Choose SOC 2/HIPAA-compliant software. 2. Migrate client data. 3. Set up alerts for deadlines/reconciliations. |
Start by automating repetitive tasks like trust account reconciliations, CLE tracking, and engagement letter generation. Use web forms linked to your practice management system to ensure conflict checks and engagement letters are never missed. Automated alerts for deadlines – whether for monthly reconciliations or annual CLE requirements – help your firm stay compliant.
AI-driven tools not only reduce violations but can also recover up to 15 additional billable hours per month. However, monitor these systems weekly, as they may fail if passwords change or apps require re-authentication. When using third-party tools, review their terms of service to ensure client data remains confidential.
“AI is transforming law firm compliance requirements by automating tasks, reducing errors, and ensuring consistency.” – Maryam Sameer, Content Writer, LegalClerk.ai
Platforms like The Legal Assistant provide automation features that simplify compliance workflows without requiring technical expertise. Their billing and document generation tools ensure critical documents are standardized and monitored automatically, supporting your firm’s compliance efforts.
Secure Insurance, Data Protection, and Ongoing Review
Once technology is in place and your team is trained, the next step is to safeguard your practice with proper insurance and strong data protection measures. These are critical for shielding your firm from malpractice claims, data breaches, and regulatory penalties. Regular reviews ensure your firm stays compliant with evolving regulations and prepared for emerging risks.
Review Malpractice and Liability Insurance Policies
Certain practice areas, like real estate, intellectual property, and securities law, come with higher risks. If your firm expands into these areas, you may need to adjust your insurance policies or pay additional premiums. Failing to notify your insurance carrier about changes in your practice could lead to denied claims.
Professional liability insurance, often referred to as legal malpractice insurance, protects against claims of negligence, errors, or omissions in legal services. Between 2019 and mid-2020, malpractice claim payouts hit record highs. Costs for this type of policy typically range from $1,200 to $2,500 annually, but high-risk areas can push premiums to $3,000–$10,000 per year. For instance, Oregon mandates a minimum of $300,000 in malpractice coverage through the Professional Liability Fund.
Cyber liability insurance is becoming a necessity. In 2020, 29% of law firms reported security breaches, yet only 36% had cyber insurance. This coverage helps manage the financial fallout from data breaches, recovery efforts, and cyberattacks. With the average cost of a data breach climbing to $4.88 million in 2024 – up 10% from the previous year – this type of protection is no longer optional.
| Insurance Type | Primary Risk Covered | Typical Annual Cost |
|---|---|---|
| Professional Liability | Negligence, errors, and omissions | $1,200–$2,500 (up to $10,000 for high-risk areas) |
| Cyber Liability | Data breaches, hacking, recovery | Varies by firm size and data volume |
| General Liability | Bodily injury, property damage | Included in Business Owner’s Policy (BOP) |
| EPLI | Employment lawsuits (harassment, discrimination) | Varies by number of employees |
When reviewing policies, pay attention to the retroactive coverage date and choose between “Defense Within Limits” (DWL) and “Defense Outside Limits” (DOL) options. DOL policies are particularly valuable for high-stakes claims since they preserve the full settlement amount.
“Inadequately insuring your firm can be more costly in the long run. From malpractice claims and cybersecurity threats to the normal risks of doing business, insurance for lawyers can go a long way to protecting your business and financial well-being.” – Sharon Miki, Clio
With insurance in place, the next focus should be on securing client data.
Ensure Client Data Privacy and Security
Protecting client data isn’t just an ethical responsibility – it’s a legal requirement with hefty penalties for non-compliance. Start by determining which regulations apply based on your location and client base. For example:
- GDPR can impose fines up to 4% of global revenue or €20 million.
- California’s CCPA allows penalties of up to $7,500 per violation.
- HIPAA Tier Four violations for willful neglect can reach $60,226 per violation, with annual caps of $1,806,757.
Begin with a data inventory and classification. Identify the types of data you handle – like personally identifiable information (PII), financial records, or protected health information (PHI) – and map out how it flows through your firm. This process highlights vulnerabilities and helps prioritize security upgrades.
Key security measures include:
- Encryption for data at rest and in transit.
- Multi-factor authentication (MFA) for all accounts.
- Role-based access control (RBAC) to restrict data access to authorized personnel.
According to the 2023 ABA Cybersecurity TechReport, 29% of law firms have experienced a security breach. MFA adds an extra layer of protection beyond standard passwords.
Develop a Written Information Security Program (WISP) and a clear data privacy policy outlining procedures for data collection, storage, and disposal. Use secure client portals for sharing sensitive documents instead of unencrypted email.
Vendor management is another critical aspect. Conduct due diligence on third-party providers and ensure Business Associate Agreements (BAAs) are in place for entities handling PHI. Review vendor contracts to confirm that client data remains confidential and isn’t used for training public AI models without explicit consent.
“Lawyers must make reasonable efforts to prevent unauthorized access or disclosure of client information.” – ABA Rule 1.6
Finally, establish a robust Incident Response Plan (IRP). Clearly define roles (such as Coordinator, IT, Legal, and Communications) and outline immediate steps for containment and notification. Some regulations, like GDPR, require notification of supervisory authorities within 72 hours of a breach.
Schedule Regular Checklist Reviews
Staying compliant requires regular updates to your policies and procedures. Assign a compliance officer or team to monitor regulatory changes and update your checklist periodically. This ensures your firm remains prepared for new risks and requirements.
Conduct quarterly reviews of your compliance checklist. These reviews should cover:
- Testing the effectiveness of technical safeguards, like encryption and MFA.
- Performing data privacy audits and risk assessments to uncover vulnerabilities.
- Documenting findings in a centralized compliance manual and assigning follow-up tasks with clear deadlines.
Stay on top of reporting requirements, such as filing annual Trust Safety Accounting Reports or registering new trust accounts with regulators. For example, Alberta requires firms to register trust accounts with the Law Society. Missing these deadlines can result in fines or even license suspension.
Review your insurance coverage annually to ensure it aligns with new practice areas and evolving risks, like cyber threats. Regular staff training on cybersecurity and confidentiality is equally important. In 2025, 61% of lawyers cited cybersecurity as their top concern with remote work, and 65% identified data privacy as a primary issue.
Tools like The Legal Assistant’s platform can simplify compliance tracking by organizing client files, reconciling trust accounts, and automating deadline alerts. While software can’t replace human oversight, it can make regular reviews more efficient and help reduce the risk of missed requirements.
Conclusion and Key Takeaways
Launching a new practice area is no small feat – it requires careful planning, legal expertise, and a rock-solid compliance system to protect your firm. From setting up separate IOLTA accounts and ensuring proper malpractice coverage to prioritizing data security and conducting regular audits, every step plays a critical role in shielding your practice from penalties and ethical issues.
The risks are real. Data breaches and malpractice claims can be costly, both financially and reputationally. That’s why a proactive approach is essential. A clear, actionable checklist combined with modern tools can simplify compliance and reduce potential pitfalls.
This is where practice management software comes into play. Tools like The Legal Assistant streamline your compliance efforts by automating trust accounting reconciliations, tracking CLE requirements, and identifying conflicts before they escalate. With features for document generation, billing management, and secure client communication, these platforms help ensure your firm stays organized and meets regulatory expectations.
“Compliance doesn’t stop at the lawyer – it scales with the firm.” – Joshua Lenon, Clio
To strengthen your compliance strategy, consider appointing a compliance officer, conducting quarterly reviews of your policies, and incorporating mandatory training for new hires. By fostering a culture of compliance from the outset, you not only protect your firm but also build trust with clients, reassuring them that their sensitive information is in safe hands.
FAQs
What steps prevent unauthorized practice of law in a new state?
To ensure you’re not stepping into unauthorized practice of law when operating in a new state, it’s crucial to follow that state’s multijurisdictional practice rules and licensing requirements. Start by securing the proper licensure and, if necessary, registering with the state bar. For interstate law firms, make sure you’re aligned with the specific regulations governing such practices.
Take the time to review the state’s guidelines to understand what activities are permitted. For instance, some states allow temporary legal services or supervised practice under certain conditions. Always stay within the boundaries of what’s allowed under the state’s rules to avoid any compliance issues.
How do I handle flat fees and retainers in an IOLTA account?
Flat fees and retainers paid upfront need to be placed in an IOLTA account and kept separate from your operating funds until they’re earned. Be sure to keep detailed records that include the amount, purpose, and date of each transaction to stay compliant. Any unearned portion must remain protected in the account. Additionally, any interest generated by IOLTA accounts is allocated to state programs supporting legal aid – not for personal use.
What should my incident response plan include for a data breach?
An effective data breach response plan should cover several key steps to handle the situation responsibly and minimize damage:
- Verification of the breach: Confirm the breach occurred, identify which systems and data were affected, and determine its scope.
- Record-keeping: Document all actions taken, preserve evidence, and maintain detailed logs for legal and investigative purposes.
- Notification procedures: Notify affected individuals, clients, or stakeholders promptly, and ensure compliance with all applicable legal and regulatory requirements.
- Communication strategies: Develop clear messaging for both internal teams and external audiences, including customers and media, to manage the situation transparently.
- Response team assembly: Assign roles and responsibilities to a dedicated team to ensure a coordinated and efficient response.
- Post-incident review: After the situation is under control, analyze what happened, assess the effectiveness of the response, and identify ways to improve future plans.
By following these steps, organizations can better safeguard client data and meet compliance requirements effectively.